
While ‘sequence-of-returns risk’ may not be something you’ve heard of, the implications of it could affect you. Worse still, it could make the difference between your pension pot providing the retirement lifestyle you want, or not.
Often referred to as ‘sequence risk’, it’s triggered when the investments within your pension drop in value just as you start to take an income from it. As a result of this, your pension pot could run dry earlier than expected, which might force you to significantly reduce your standard of living later on.
Read on to discover more about sequence risk, and the steps you could take to reduce its impact on your retirement. Before you do, however, let’s look at the relationship between investments and pensions.
Broadly speaking, pensions hold investments
If you have a defined contribution (DC) pension, otherwise known as a ‘money purchase scheme’, the contributions you make are placed into a range of assets, which can include:
stocks and shares
commercial property
government bonds.
Broadly speaking, stocks and shares are used to expose your pension pot to higher levels of growth over the long term. This is because historically, stocks and shares have tended to provide greater returns than cash, which ensures the money within your retirement fund maintains its spending power.
To illustrate this, you might want to consider the following graph, which shows the performance of global equities and a medium risk 60:40 multi-asset portfolio between 1 January 2005 and 31 December 2025.
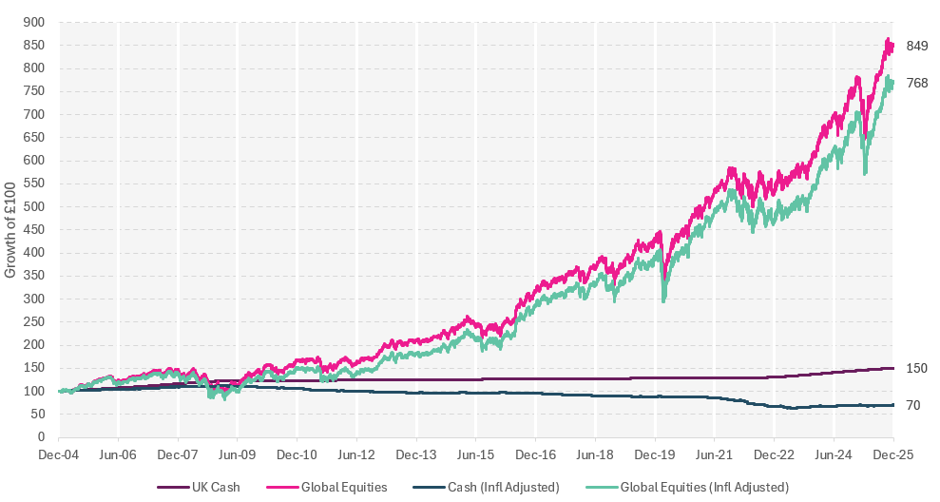 Data sourced from Morningstar by AFH Wealth Management. The 60:40 portfolio allocates 60% to MSCI ACWI and 40% to Bloomberg Global Aggregate.
As you can see, the investment portfolio provided significant returns over the long-term when compared to cash savings. Furthermore, this is still the case after inflation is considered. Always remember that historical returns are not a reliable indicator of future returns.
That said, the growth provided by stocks and shares carries risk. While they have the potential to grow significantly in value when the stock market rises, they can also drop substantially in value when it suffers a downturn.
If this happens and your pension’s value plummets when you first draw an income from it, sequence risk may become an issue. Take a look at our pensions guide for further tips.
Sequence risk could shrink the size of your pension pot
If, when you retire, the markets are rising, the amount you withdraw from your pension will be covered by the rising value of your shares. If, on the other hand, the markets are falling, the value of your shares could fall, meaning you’ll need to sell more of them to generate the income you want.
In other words, the income shortfall will need to be covered by selling more of the capital within your pension.
As a result, you will be depleting the investments within your pension much more quickly than expected, which might mean it can no longer provide the income you need. If you continue taking the income and capital needed to support your lifestyle in retirement, you could inadvertently deplete your pension pot much earlier than expected.
This could put your financial security at risk and may even mean you have to significantly reduce your standard of living later in life.
It’s not all bad news though, as there are steps you might be able to take to protect your pension from sequence risk if the markets take a downturn when you retire. The following are three you might want to consider.
Live off other assets
If you have savings or other assets, such as investments, you might want to consider using these to draw an income when you first retire. Doing this preserves your pension pot and may give it the time needed to recover before you start to draw an income from it.
Consider an annuity
With an annuity, you exchange the value of your pension pot for a guaranteed income. This could be for the rest of your life, or for a set period of time.
As annuities are not affected by the stock market, your long-term income will not be impacted if the markets fall in the first few months of your retirement. This could provide peace of mind that you’ll receive the income you need to maintain your standard of living (as long as it’s inflation-proofed).
Defer retirement
If possible, deferring your retirement could be an extremely shrewd move. It allows the markets to recover, meaning your pension will not be affected by sequence risk when you access it.
Furthermore, you can continue to make contributions to your pension pot, which could boost its value and provide a higher standard of living when you stop working.
Get in touch
If you’re approaching retirement and would like to understand your options, and how sequence risk could affect you, please call us on 01527 577775. Alternatively, contact us to speak to one of our advisers, as we’d be happy to help.