
When it comes to financial strategies, you might think that investing and saving are at odds. In reality, however, the most effective investment strategy typically includes cash savings.
While historically investing has tended to expose money to greater growth potential than cash savings over the long term, it’s essential to have enough ‘cash in hand’ to deal with life’s unexpected events.
If you don’t, it could spell disaster for your investment plan and your wider wealth. As part of National Savings Week, which started on Monday 21 September, let’s look at the importance of having adequate amounts of savings when investing.
Why are savings central to a good investment plan?
Ensuring you have adequate savings provides a financial lifeline if something unexpected, and unwelcome, happens in your life. This could be, for example, the diagnosis of a serious illness meaning you’re unable to work for several months, or an expensive bill such as a major repair to the house.
Having an adequate ‘emergency’ or ‘rainy day’ fund, means you’re less likely to use expensive credit cards or a loan to deal with the expenditure. Either of these could result in high charges or interest, which could significantly increase the overall cost of dealing with the problem.
More importantly when it comes to investing, having an emergency fund could help to ensure you won’t need to sell your investments to maintain your lifestyle if you’re unable to work, or settle a large bill. Let’s look at why this is so important next.
What happens if I need to sell my investments?
If you do need to sell your investments your money will miss out on any future growth potential. This could be significant over the long term and may mean you’re unable to meet your financial objectives.
More worrying is what happens if you are forced to sell your investments to deal with one of life’s curve balls during a stock market downturn. If you do, you’re more likely to turn a significant loss on paper into a reality, meaning you could get back substantially less than your original investment.
The worst-case scenario of this might be that you then have to reduce your standard of living to cope with the loss. Having a large enough emergency fund to deal with the unexpected means you can remain invested and ride out the downturn.
As a result, your money will be exposed to growth potential when the markets recover – which historically, they’ve tended to do.
How much should I have in my emergency fund?
The amount you will need in your emergency fund largely depends on your circumstances and how much you’re comfortable having in it. Some people feel better with larger amounts in their fund, but broadly speaking, you should have enough to cover your essential expenditure for three to six months.
Yet an article by FT Adviser in September 2026 suggests that 57% of people with an emergency fund could only cover three months of essential costs, or less. It points to research that found that many Britons who believe they’re financially prepared for the worst may still run out of money within weeks of losing their income or dealing with a major repair.
What sort of account is best to keep an emergency fund in?
Your emergency fund should be held in an easy to access cash account, which is separate from your main current account. The latter ensures you won’t inadvertently spend some or all of your emergency fund, which could then create problems when the unexpected happens.
As you need to be able to access your fund at a moment’s notice, avoid putting it into an account that has a long notice period for withdrawals, or has withdrawal fees.
Can I have too much money in my emergency fund?
While you should ensure you have sufficient cash in your fund, care needs to be taken not to have too much in it. This is because your emergency fund needs to be kept in cash accounts, which typically offer lower levels of potential growth when compared with investing.
Worse still, the value of money in cash accounts can drop in real term value because of inflation. This measures the rising cost of goods and services over time, which reduces your money’s future spending power.
To illustrate how inflation devalues wealth in real terms, you might want to consider the Bank of England's inflation calculator. It reveals that you needed £194.90 in August 2026 to have the same spending power of £100 in August 2001.
As such, your money needed to grow nearly 95% during the 25-year period just to keep pace with inflation. If it didn't, your money would have been dropping in value in real terms.
Also consider the following illustration, which shows the performance of global equities and a medium risk 60:40 multi-asset portfolio between 1 January 2005 and 31 December 2025.
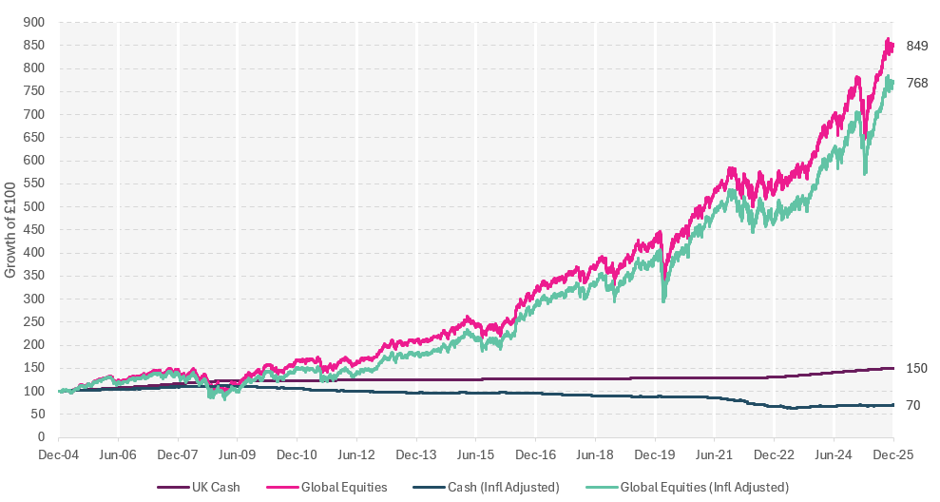
Data sourced from Morningstar by AFH Wealth Management. The 60:40 portfolio allocates 60% to MSCI ACWI and 40% to Bloomberg Global Aggregate.
As you can see, the multi-asset portfolio provided significantly higher levels of growth than cash savings did during the period. This is still the case when inflation is taken into account, which means investing could help to maintain your cash’s long-term spending power.
So while it’s important to have enough cash savings to deal with life’s curve balls, it’s vital not to hold too much, as it could expose your wealth to the effects of inflation. Always remember that investing carries risk, and past performance is no guarantee of future performance. You may receive less than you originally invested.
Get in touch
Ensuring you have the right amount in your emergency fund is the bedrock of a good financial plan. As one of the UK’s largest truly independent financial advice companies, we understand this.
If you would like to discuss how we may be able to help you, please call us on 0333 010 0008 to arrange a no obligation initial meeting with one of our Independent Financial Advisers.